Featured · · 3 min read
Buying an Investment Property? Here's How Rental Income Can Increase Your Loan Eligibility
Most buyers assume their home loan eligibility is based purely on their salary and existing income.
While that is usually true, there is one strategy that many investors overlook.
If you're purchasing a tenanted property, banks may recognise a portion of the rental income during the loan assessment process.
In some cases, this can increase your borrowing power by hundreds of thousands of dollars.
For investors looking to maximise their property budget, understanding how rental income is assessed can make a significant difference.
Most Buyers Don't Know This
When calculating home loan eligibility, banks typically look at:
- Salary income
- Bonuses and commissions
- Self-employed income
- Existing financial commitments
However, if the property you're purchasing already has a tenant in place, some banks may also consider the rental income generated by that property.
This additional income can help improve your loan eligibility and potentially allow you to purchase a higher-value property.
When Can Rental Income Be Used?
Rental income is generally considered when:
✅ The property is already tenanted
✅ The tenancy agreement has at least 6 months remaining
✅ The tenancy agreement is properly stamped
If these conditions are met, banks may factor the rental income into your home loan assessment.
How Much Rental Income Is Recognised?
Most banks do not recognise 100% of rental income.
Instead, they typically recognise approximately 70% of the rental amount.
For example:
Monthly Rental Income: $5,000
Recognised Rental Income:
$5,000 × 70%
= $3,500 per month
That additional recognised income can significantly improve your borrowing power.
Real Example: Same Buyer, Different Outcome
Let's compare two scenarios.
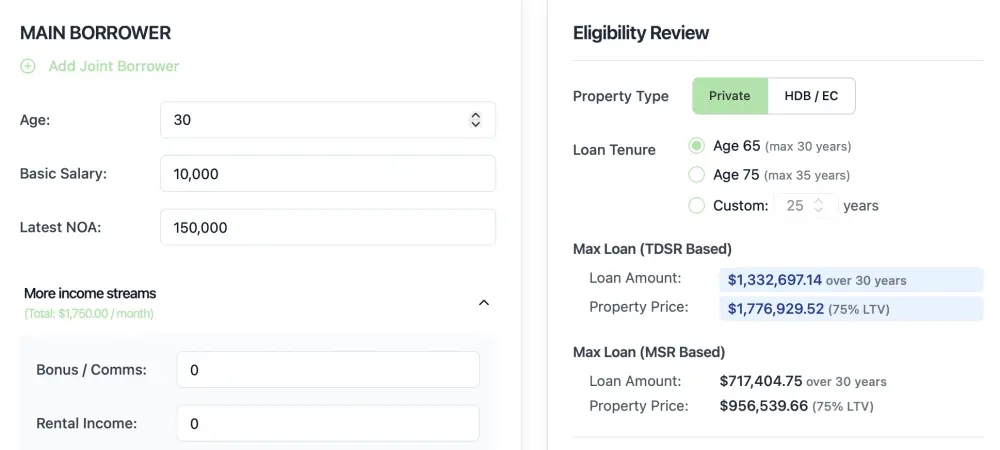
Scenario 1: Without Rental Income
Borrower Profile:
- Age: 30
- Salary: $10,000
- NOA: $150,000
Maximum Loan Eligibility:
- Loan Amount: ~$1.33M
- Estimated Property Budget: ~$1.78M
Scenario 2: With Rental Income
Same buyer.
Same age.
Same income.
The only difference?
The property generates $5,000 per month in rental income.
Maximum Loan Eligibility:
- Loan Amount: ~$1.74M
- Estimated Property Budget: ~$2.31M
The Difference
By recognising rental income:
👉 Loan eligibility increased by more than $400,000
👉 Property budget increased by more than $500,000
Same buyer.
Same income.
Same age.
One additional recognised income stream.
This demonstrates why understanding loan structuring is just as important as understanding interest rates.
Why This Matters For Property Investors
Many investors focus solely on:
- Saving a larger downpayment
- Finding the right property
- Negotiating a better purchase price
But often overlook how the loan is structured.
A properly structured loan assessment can potentially:
- Increase borrowing power
- Expand property options
- Improve investment opportunities
- Help investors acquire assets that may otherwise seem out of reach
The goal isn't simply to borrow more.
The goal is to ensure you're assessed correctly based on the full financial picture available.
Don't Rely Solely On Online Calculators
Most online mortgage calculators do not account for:
- Rental income recognition
- Bank-specific assessment methods
- Income structuring opportunities
- Special lending scenarios
This is why two buyers with similar incomes can receive very different loan outcomes.
The right strategy often matters just as much as the numbers themselves.
Plan Ahead Before You Buy
If you're considering purchasing an investment property, it's worth reviewing:
- Whether the tenancy qualifies
- Which banks recognise rental income
- How much rental income can be used
- The impact on your overall loan eligibility
Understanding these factors before making an offer can help you avoid surprises and maximise your options.
Free Loan Eligibility Review
Not sure whether rental income can be used for your purchase?
Our team can help you review:
- Home loan eligibility
- Rental income assessment
- Property affordability
- Bank options and loan structuring
🎁 Claim your complimentary loan eligibility review today.
Written by Loan Experts. General information, not personal advice.