Featured · · 3 min read
How a $50K Car Loan Reduced Home Loan Eligibility by Over $300K
Most buyers think banks care about one thing:
👉 How much debt you have left.
But when it comes to home loans, that’s not actually the main issue.
Banks care more about:
- Your monthly obligations
- Your debt servicing ratio (TDSR)
- Your ability to service monthly repayments
This means even a relatively “small” car loan can massively reduce your home loan eligibility.
And most buyers only realise this after they’ve already started viewing properties.
The Hidden Problem With Car Loans
One of the most overlooked factors affecting home loan eligibility is:
👉 Monthly liabilities.
This includes:
- Car loans
- Personal loans
- Credit card debt
Most buyers assume:
“I only have a small amount left on my car loan.”
But banks don’t assess based on how much loan is remaining.
They assess based on:
- Monthly instalment
- Monthly debt obligations
- TDSR impact
That difference is important.
Because even a car loan with roughly $50K–$60K remaining can still significantly reduce your property loan eligibility.
Real Example: Same Income, Different Outcome
We recently compared the same client profile under 2 scenarios.
Scenario 1 — Existing Car Loan
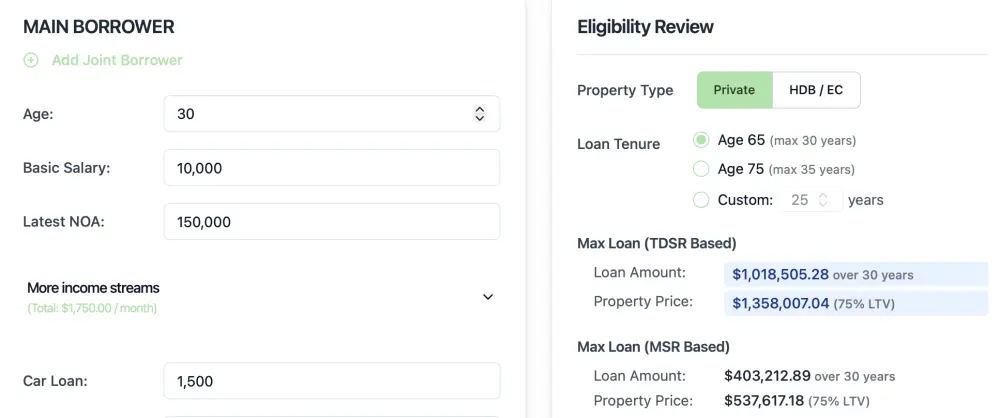
- Monthly car instalment: ~$1,500/month
- Remaining car loan: approximately ~$50K–$60K
Scenario 2 — Car Loan Cleared
- Same income
- Same profile
- No car liability
The loan difference was substantial.
Before Clearing the Car Loan
Maximum home loan eligibility:
👉 Approximately $1.018M
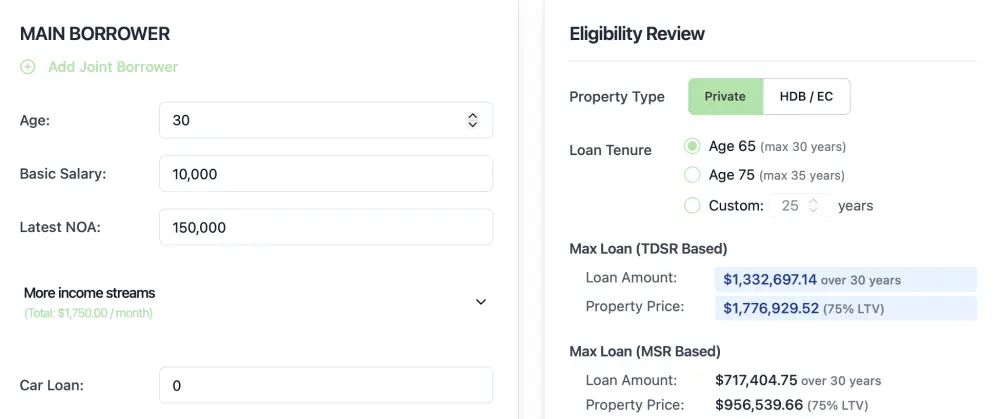
After Clearing the Car Loan
Maximum home loan eligibility:
👉 Approximately $1.332M
The Difference
By removing the car liability:
👉 Home loan eligibility increased by approximately $314K
That’s a massive increase created without:
- Increasing income
- Changing jobs
- Adding another borrower
The only difference:
👉 Removing a monthly liability.
Why Does This Happen?
Singapore banks assess home loans using TDSR (Total Debt Servicing Ratio).
This means your monthly debt obligations directly affect:
- How much monthly instalment you can support
- Your maximum loan eligibility
So even though:
- The remaining car loan may not seem large
- The car may already be mostly paid off
The monthly instalment still reduces your borrowing power significantly.
Why This Matters
A lower loan eligibility can affect:
- What property you can buy
- Whether you can upgrade
- Your purchasing options
- Your flexibility during the purchase process
In some cases, buyers may:
- Waste time viewing properties outside their actual budget
- Face issues after OTP
- Need to revise plans late into the purchase journey
This is why proper planning before buying property matters.
Should You Clear Your Car Loan Before Buying Property?
Not always.
It depends on:
- Your cash position
- Remaining car loan tenure
- Property timeline
- Overall financial strategy
However, this example highlights an important point:
👉 Small liabilities can create a surprisingly large impact on your home loan.
Even smaller obligations can matter too.
Some buyers get caught by:
- Appliance instalment plans
- Buy-now-pay-later schemes
- Short-term financing
Even if the instalment only lasts 3–6 months, banks may still factor it into the assessment if it appears during application.
That’s why reviewing liabilities early is important before committing to a property purchase.
Pro Tip: Plan Ahead
If you’re planning to buy property:
- Review liabilities early
- Assess your loan eligibility properly
- Avoid waiting until OTP
Certain adjustments may take:
- 1–2 months to reflect
- Longer depending on the bank
The earlier you plan, the more flexibility and options you’ll have.
Need Help Reviewing Your Loan Eligibility?
At Loan Experts Singapore, we help buyers assess:
- Loan eligibility
- Liability impact
- Ways to potentially improve borrowing capacity
- Suitable bank options
You can also:
- Check latest interest rates
- Use mortgage calculators
- Explore refinancing options
Written by Loan Experts. General information, not personal advice.